
Navigating the complex landscape of tax regulations is an essential aspect of running a successful business. You must understand that compliance is not just a legal obligation; it is also a critical component of your overall financial strategy. Failing to adhere to tax laws can result in severe penalties, including fines and interest charges, which can significantly impact your bottom line.
Therefore, staying informed about the latest tax regulations and ensuring that your business complies with them is paramount. To facilitate compliance, consider investing in professional accounting services or tax advisory support. These experts can help you understand the intricacies of tax laws and ensure that you are taking advantage of any available deductions or credits.
Additionally, maintaining organized financial records will simplify the process of filing taxes and reduce the likelihood of errors. By prioritizing compliance with tax regulations, you not only protect your business from potential legal issues but also foster a culture of accountability and transparency within your organization.
Effective Decision Making
Effective decision-making is at the heart of successful business management. As a business owner or manager, you are often faced with choices that can significantly impact your organization’s trajectory. To make informed decisions, you must rely on accurate data and insights derived from your financial records.
This means that having a clear understanding of your financial position is essential for evaluating options and determining the best course of action. Moreover, effective decision-making involves considering both short-term and long-term implications. You should weigh the potential benefits and risks associated with each choice, taking into account how they align with your overall business strategy.
By fostering a culture of collaboration and encouraging input from your team, you can enhance the decision-making process. Engaging diverse perspectives can lead to more innovative solutions and ultimately contribute to the success of your business.
Clear Picture of Business Performance
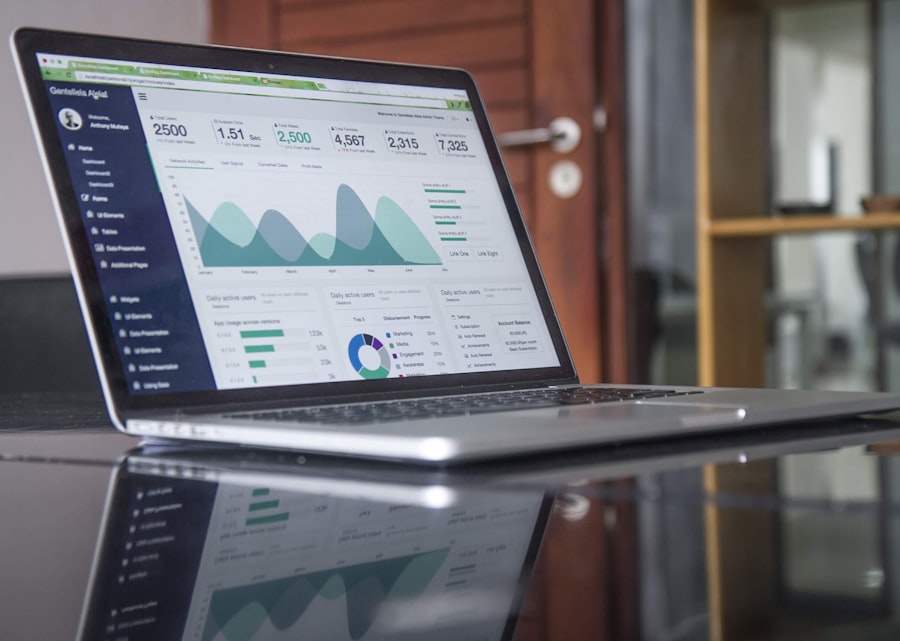
Having a clear picture of your business performance is vital for identifying strengths and weaknesses within your organization. You need to regularly analyze key performance indicators (KPIs) to gauge how well your business is doing in various areas, such as sales, profitability, and customer satisfaction. This analysis allows you to pinpoint areas that require improvement and develop strategies to enhance overall performance.
In addition to tracking KPIs, consider implementing regular performance reviews to assess progress against your goals. These reviews provide an opportunity to reflect on achievements and challenges while fostering accountability among team members. By maintaining transparency about performance metrics, you create an environment where everyone is aligned with the company’s objectives and motivated to contribute to its success.
Ultimately, having a clear understanding of your business performance empowers you to make data-driven decisions that drive growth.
Facilitating Access to Funding
Accessing funding is often a critical challenge for businesses, especially during periods of expansion or when facing unexpected expenses. You must recognize that having a solid financial foundation can significantly enhance your ability to secure funding from various sources, including banks, investors, or government programs. Lenders and investors are more likely to support businesses that demonstrate sound financial management practices and a clear understanding of their financial health.
To facilitate access to funding, ensure that your financial statements are accurate and up-to-date. This includes balance sheets, income statements, and cash flow statements that reflect your business’s current position. Additionally, developing a comprehensive business plan that outlines your goals, strategies, and projected financial performance can help instill confidence in potential investors or lenders.
By presenting a well-prepared case for funding, you increase your chances of obtaining the necessary resources to fuel your business’s growth.
Minimizing Risk of Errors and Fraud
In today’s fast-paced business environment, minimizing the risk of errors and fraud is more important than ever. You must be proactive in implementing internal controls and best practices to safeguard your financial assets and maintain the integrity of your financial reporting. This includes establishing clear procedures for handling transactions, conducting regular audits, and providing training for employees on ethical practices.
Additionally, leveraging technology can play a significant role in reducing the risk of errors and fraud. Utilizing accounting software with built-in safeguards can help automate processes and minimize human error. Furthermore, employing data analytics tools can assist in identifying unusual patterns or discrepancies in financial transactions that may indicate fraudulent activity.
By prioritizing risk management strategies, you not only protect your business from potential losses but also foster trust among stakeholders and customers. In conclusion, building a strong foundation for financial stability is essential for any business aiming for long-term success. By ensuring compliance with tax regulations, making effective decisions based on accurate data, maintaining a clear picture of performance, facilitating access to funding, and minimizing risks associated with errors and fraud, you position yourself for growth and resilience in an ever-changing marketplace.
Embracing these principles will not only enhance your financial health but also contribute to the overall sustainability of your organization in the years to come.
Accurate bookkeeping is crucial for small businesses to maintain financial health and make informed decisions. In addition to proper bookkeeping, having a fractional CFO or controller can provide valuable financial expertise and guidance. To learn more about the benefits of having a fractional CFO or controller for your small business, check out this article on Fractional CFO/Controller. At JPS, our team of financial experts is dedicated to helping small businesses thrive. To meet our team and learn more about our services, visit Meet the Team.
FAQs
What is bookkeeping?
Bookkeeping is the process of recording and organizing a business’s financial transactions, including purchases, sales, receipts, and payments.
Why is accurate bookkeeping important for small businesses?
Accurate bookkeeping is important for small businesses because it helps them track their financial health, make informed business decisions, comply with tax regulations, and secure funding from lenders or investors.
What are the consequences of inaccurate bookkeeping for small businesses?
Inaccurate bookkeeping can lead to financial mismanagement, cash flow problems, tax penalties, and legal issues. It can also hinder a business’s ability to secure funding or attract potential buyers.
What are the key components of accurate bookkeeping for small businesses?
The key components of accurate bookkeeping for small businesses include maintaining organized financial records, reconciling bank statements, tracking expenses and income, and preparing financial statements such as balance sheets and income statements.
How can small businesses ensure accurate bookkeeping?
Small businesses can ensure accurate bookkeeping by using accounting software, hiring a professional bookkeeper or accountant, staying organized with receipts and invoices, and regularly reconciling their financial records.